2026 Medical Debt Management: Reduce Payments by 20% – Your Ultimate Guide
Anúncios
Anúncios
The 2026 Guide to Medical Debt Management: Reducing Your Payments by 20%
In 2026, the landscape of healthcare and personal finance continues to evolve, making effective medical debt management more crucial than ever. For millions, medical bills represent a significant financial burden, often unexpected and overwhelming. The good news is that with the right strategies and a proactive approach, it’s entirely possible to navigate these challenges and significantly reduce your payments – often by 20% or more. This comprehensive guide will equip you with the knowledge and tools needed to tackle medical debt head-on, protect your financial health, and reclaim peace of mind.
Understanding the intricacies of medical billing, insurance policies, and debt collection practices is the first step towards successful medical debt management. Many individuals simply pay what they are billed without questioning, unaware of the numerous avenues available for relief. From negotiating directly with providers to exploring financial assistance programs and understanding legal protections, there are multiple pathways to lighten your load. This article will delve into each of these strategies, offering practical advice and actionable steps tailored for the 2026 financial environment.
The Rising Tide of Medical Debt: Why 2026 Demands Proactive Management
Medical debt has become a pervasive issue across the United States, impacting individuals and families from all walks of life. Despite advancements in healthcare and insurance coverage, out-of-pocket costs continue to rise, leaving many with substantial bills even after insurance contributions. The reasons are multifaceted: high deductibles, co-pays, uncovered services, and the sheer complexity of medical billing codes contribute to a system that can feel impossible to navigate without expert guidance.
Anúncios
As we move further into 2026, healthcare costs are projected to continue their upward trajectory. New technologies, pharmaceutical innovations, and administrative overhead all play a role in this increase. For consumers, this translates into a greater need for vigilance and robust medical debt management strategies. Ignoring medical bills is not an option, as it can lead to severe consequences, including damaged credit scores, collections calls, and even legal action. Therefore, understanding the current climate and preparing with effective strategies is paramount.
The mental and emotional toll of medical debt cannot be overstated. It can lead to stress, anxiety, and a feeling of hopelessness. Our goal is to empower you with the information to transform that despair into actionable hope, demonstrating that reducing your medical payments by a significant margin is an achievable reality. Let’s explore how to make medical debt management a manageable and successful endeavor.
Step 1: Scrutinize Your Medical Bills with a Fine-Tooth Comb
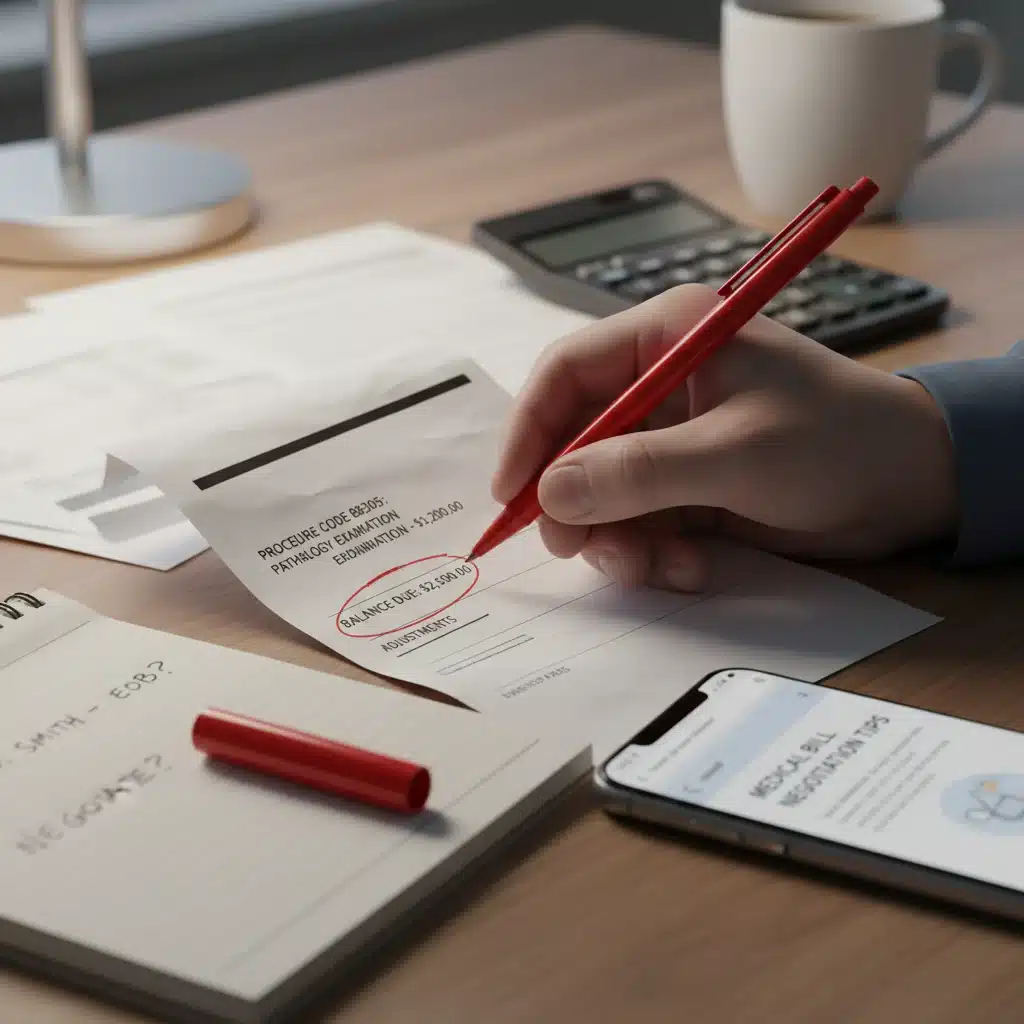
One of the most critical initial steps in effective medical debt management is to meticulously review every medical bill you receive. Errors in medical billing are surprisingly common and can lead to inflated costs. These errors can range from incorrect coding and duplicate charges to charges for services you never received. Do not assume that the bill is accurate simply because it came from a healthcare provider.
What to Look For When Reviewing Bills:
- Incorrect Patient Information: Ensure your name, address, and insurance details are correct.
- Duplicate Charges: Check for services or items billed more than once.
- Unbundled Charges: Sometimes, services that should be grouped under a single charge are billed separately, increasing the overall cost.
- Incorrect Codes: Medical billing codes (CPT codes, ICD-10 codes) are complex. An incorrect code can lead to a higher charge or a denial by your insurance.
- Charges for Unreceived Services: Verify that all services, tests, and medications listed were actually provided to you.
- Insurance Adjustments: Make sure your insurance company’s adjustments and payments are accurately reflected.
- Provider Network Status: Confirm that all providers involved were in-network, if applicable to your plan, to avoid surprise out-of-network charges.
If you identify any discrepancies, contact the billing department of the healthcare provider immediately. Request an itemized bill, which provides a detailed breakdown of all charges. This document is essential for a thorough review and for challenging any questionable items. Many facilities will provide this upon request. Remember, you have a right to understand exactly what you are being charged for. This careful review is a cornerstone of proactive medical debt management.
Step 2: Understand Your Insurance’s Role and Explanation of Benefits (EOB)
Your insurance company plays a pivotal role in your medical debt management. Before you even receive a bill from a provider, your insurance company typically sends an Explanation of Benefits (EOB). The EOB is not a bill, but a detailed statement explaining what medical services were covered, what the insurer paid, and what amount you are responsible for. It’s crucial to compare your EOB with the actual bill from the provider.
Key Elements of an EOB:
- Date of Service: Matches the date on your provider’s bill.
- Provider Name: Ensures the correct facility or doctor is listed.
- Service Description: A brief description of the medical service received.
- Amount Billed: The original charge from the provider.
- Allowed Amount: The amount your insurance company will pay for the service, based on their negotiated rates.
- Amount Paid by Insurer: How much your insurance actually paid.
- Patient Responsibility: The amount you owe after insurance, including deductibles, co-pays, and co-insurance.
Discrepancies between your EOB and the provider’s bill should be investigated. If the provider’s bill is higher than what your EOB states you owe, it’s possible the provider made an error, or there’s a miscommunication with your insurer. Contact both your insurance company and the provider’s billing department to clarify. Understanding your EOB is a powerful tool in your medical debt management arsenal, ensuring you don’t overpay due to administrative mix-ups.
Step 3: Negotiate Directly with Healthcare Providers
Once you’ve thoroughly reviewed your bills and EOBs, the next critical step in medical debt management is to negotiate directly with the healthcare provider. Many hospitals and clinics are willing to negotiate the total amount owed, especially if you are uninsured or underinsured, or if you can pay a portion upfront. They often prefer to receive some payment directly rather than dealing with collection agencies or writing off the debt entirely.
Strategies for Successful Negotiation:
- Ask for a Discount for Upfront Payment: If you can pay a lump sum, even a portion of the total, ask for a significant discount. Many providers offer 10-30% off for immediate payment.
- Request a Hardship Discount: If you are experiencing financial difficulties, explain your situation. Hospitals often have charity care policies or financial assistance programs. Be prepared to provide documentation of your income and expenses.
- Negotiate the Billed Amount: Challenge any questionable charges identified in your review. Use your research on typical costs for the services received (e.g., from fair health consumer websites) to argue for a lower price.
- Set Up a Payment Plan: If paying a lump sum isn’t feasible, ask for an interest-free payment plan that fits your budget. Many providers are amenable to this, allowing you to pay over several months or even years.
- Speak to the Right Person: Always ask to speak with the billing department manager or a patient advocate. These individuals often have more authority to make decisions regarding discounts or payment arrangements.
- Document Everything: Keep a detailed record of all communications, including dates, names of people you spoke with, what was discussed, and any agreed-upon terms.
Persistence is key in negotiation. Don’t be afraid to make multiple calls or send written requests. Your goal is to reduce your total obligation, and these conversations are central to effective medical debt management. Aim for that 20% reduction, but don’t stop there if more is possible.
Step 4: Explore Financial Assistance Programs and Charity Care
For individuals facing significant medical debt, financial assistance programs and charity care can be a lifesaver. Many hospitals, particularly non-profit ones, are legally required to offer financial aid to eligible patients. These programs can reduce or even eliminate your medical bills, depending on your income and family size.
Types of Assistance:
- Hospital Charity Care: Most non-profit hospitals have policies to provide free or discounted care to low-income patients. Eligibility criteria vary, but generally, they consider income relative to the federal poverty level.
- State and Local Programs: Some states and local governments offer programs to help residents with medical costs or debt. Research what’s available in your area.
- Disease-Specific Foundations: If your debt is related to a specific illness (e.g., cancer, diabetes), numerous non-profit organizations offer financial assistance for treatment, medications, or living expenses.
- Medicaid Expansion: In states that have expanded Medicaid, more low-income adults may qualify for comprehensive health coverage, which can retroactively cover some past medical expenses.
To apply for these programs, you’ll typically need to provide documentation of your income, assets, and household size. It’s important to apply as soon as possible, as some programs have deadlines or require applications within a certain timeframe after receiving services. Leveraging these resources is a smart and often underutilized aspect of medical debt management.
Step 5: Consider Professional Help: Medical Bill Advocates and Financial Counselors
When the complexities of medical debt management become too overwhelming, or if your efforts haven’t yielded the desired results, professional help can be invaluable. Medical bill advocates and non-profit credit counseling agencies specialize in navigating the healthcare billing system and negotiating on your behalf.
How Professionals Can Help:
- Medical Bill Advocates: These professionals review your bills, identify errors, and negotiate with providers and insurance companies. They often work on a contingency basis, taking a percentage of the savings they achieve for you, or charge a flat fee. Their expertise can uncover significant savings that you might miss.
- Non-Profit Credit Counseling Agencies: These organizations offer free or low-cost advice on managing all types of debt, including medical debt. They can help you create a budget, understand your options, and even set up a Debt Management Plan (DMP) if appropriate. Be sure to choose an accredited agency.
- Attorneys Specializing in Medical Debt: In severe cases, such as when a medical provider is suing you for unpaid bills, consulting an attorney who specializes in medical debt or consumer law might be necessary.
While there might be a cost associated with these services, the potential savings and reduction in stress can far outweigh the expense. When choosing a professional, always check their credentials, read reviews, and understand their fee structure upfront. This strategic move can be a game-changer in your pursuit of effective medical debt management.
Step 6: Understanding Your Rights and Protections Against Medical Debt Collectors
If your medical debt goes unpaid for an extended period, it may be sold to a collections agency. This can add another layer of stress, but it’s crucial to understand your rights and the protections available to you. The Fair Debt Collection Practices Act (FDCPA) regulates how debt collectors can interact with consumers.
Key Rights Under FDCPA:
- Right to Request Validation: Within 30 days of receiving a collection notice, you can send a written request to the collector asking for validation of the debt. This forces them to prove you owe the debt and that they have the right to collect it.
- Prohibition of Harassment: Collectors cannot harass, oppress, or abuse you. This includes repeated calls, threats of violence, or using obscene language.
- Limits on Communication: Collectors cannot call you at unreasonable times (e.g., before 8 AM or after 9 PM, unless you agree). They also cannot contact you at work if you tell them not to.
- Accuracy of Information: Collectors cannot make false statements or misrepresentations about the debt.
- Credit Reporting: Medical debt cannot appear on your credit report for a certain period, typically one year, giving you time to resolve it. In 2023, the major credit bureaus (Equifax, Experian, and TransUnion) removed all medical debt under $500 from credit reports, and paid medical collections are no longer reported. This is a significant improvement for consumers in 2026.
If a debt collector violates your rights, you can report them to the Consumer Financial Protection Bureau (CFPB) or your state’s attorney general. Knowing your rights empowers you to stand up to aggressive collection tactics and ensures a fairer process in your medical debt management journey.
Step 7: Proactive Measures for Future Medical Debt Prevention
While this guide focuses on managing existing debt, the best strategy is always prevention. Taking proactive steps can significantly reduce your risk of accumulating future medical debt.
Preventative Strategies:
- Review Your Insurance Plan Annually: Understand your deductible, out-of-pocket maximum, co-pays, and co-insurance. Choose a plan that best fits your health needs and financial situation.
- Utilize In-Network Providers: Always confirm that all doctors, specialists, and facilities are in your insurance network to avoid higher out-of-network costs.
- Get Pre-Authorizations: For elective procedures or expensive treatments, ensure your insurance pre-authorizes the services.
- Build an Emergency Fund: Having savings specifically for unexpected medical expenses can prevent debt accumulation.
- Use Health Savings Accounts (HSAs) or Flexible Spending Accounts (FSAs): These tax-advantaged accounts can help you save for and pay for qualified medical expenses.
- Ask for Cost Estimates: Before scheduled procedures, ask your provider for an estimate of the total cost and your expected out-of-pocket share.
- Understand Surprise Billing Protections: The No Surprises Act, effective in 2022, protects consumers from surprise medical bills from out-of-network providers in emergency situations and for certain non-emergency services at in-network facilities. Familiarize yourself with these protections in 2026.
By implementing these preventative measures, you can significantly reduce the likelihood of facing substantial medical debt in the future, making your overall medical debt management much simpler and less stressful.
Conclusion: Taking Control of Your Medical Debt in 2026
Navigating the complexities of medical debt can feel like an uphill battle, but it is a fight you can win. By adopting a systematic and proactive approach to medical debt management, you can significantly reduce your financial burden, often by 20% or more. This involves meticulously reviewing your bills, understanding your insurance, negotiating with providers, exploring financial aid, and knowing your rights against collectors.
Remember, you are not alone in this struggle, and there are numerous resources and strategies available to help. The key is to be persistent, informed, and assertive in advocating for your financial well-being. Don’t be afraid to ask questions, challenge charges, and seek professional assistance when needed. With the strategies outlined in this 2026 guide, you can confidently tackle your medical debt, achieve financial stability, and look forward to a healthier, less stressful future.
Start today by pulling out those medical bills and beginning your review. Every step you take, no matter how small, brings you closer to effective medical debt management and financial freedom. Your health, both physical and financial, is worth fighting for.